For many people living in or planning to move to Greater Noida West, one of the biggest financial decisions in 2026 is whether to continue paying rent or buy a home with a home loan.
Rent provides flexibility and usually requires a smaller initial financial commitment. Buying a flat, on the other hand, requires a down payment, home loan EMI, registration expenses, maintenance, and other costs—but it also gives you ownership of an asset.
So, what is better in 2026: paying rent or paying a home loan EMI in Greater Noida West?
The answer depends on your income, savings, property price, expected stay, loan terms, rent level, investment alternatives, and long-term plans.
This guide compares home loan EMI vs rent in Greater Noida West and explains the factors you should consider before making a decision.
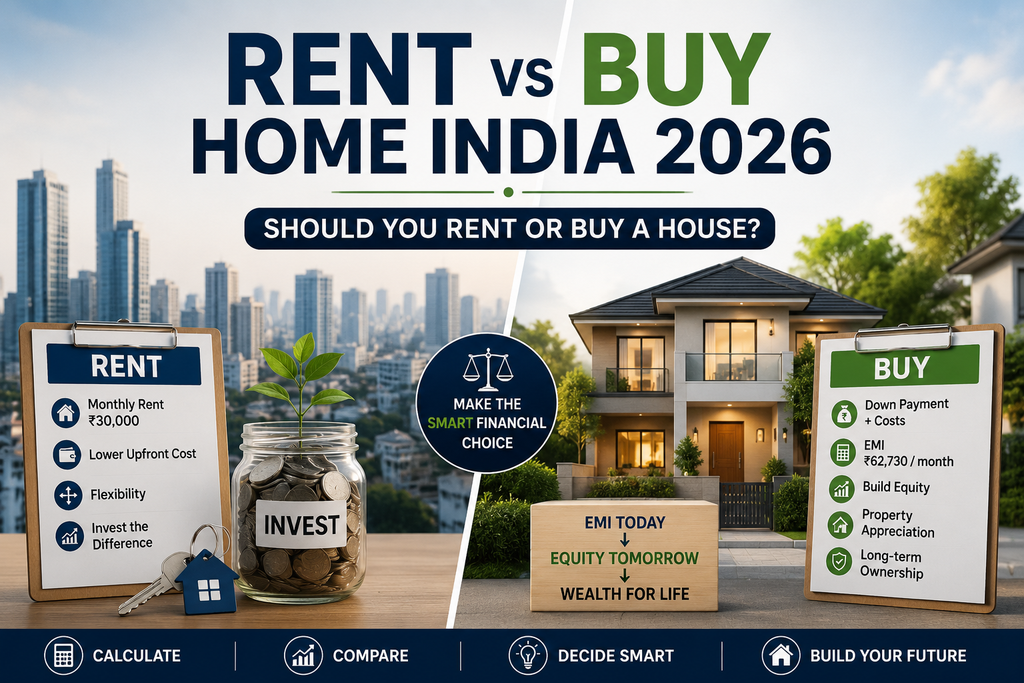
Home Loan EMI vs Rent: The Basic Difference
When you rent a flat, your monthly payment gives you the right to use the property for a specific period.
When you purchase a flat using a home loan, your monthly EMI helps repay the money borrowed to purchase the property. A portion of the EMI goes toward interest, while another portion reduces the outstanding principal.
For example:
Renting:
₹20,000 monthly rent × 12 months = ₹2.40 lakh per year
Buying:
₹30,000 monthly EMI × 12 months = ₹3.60 lakh per year
At first glance, renting appears cheaper.
But this comparison is incomplete because the homeowner is building ownership in the property, while the tenant does not acquire ownership of the rented home.
At the same time, buying has additional costs and risks that renters do not face.
Therefore, EMI vs rent should never be treated as a simple monthly-payment comparison.
Why Greater Noida West Matters in This Comparison
Greater Noida West has developed into a significant residential market for people looking for apartments in the wider NCR region.
The area attracts:
- First-time homebuyers
- Working professionals
- Families
- Investors
- People upgrading from rented accommodation
- Buyers looking for 2 BHK and 3 BHK homes
For someone already renting in Greater Noida West, the decision becomes particularly relevant.
Instead of continuing to pay rent every month, a buyer may consider using a home loan to purchase a residential property.
However, buying only makes financial sense when the property, loan and holding period fit the buyer’s circumstances.
What Does Your Rent Actually Give You?
Rent provides several advantages that should not be ignored.
1. Lower Initial Financial Requirement
A tenant generally needs:
- Security deposit
- First month’s rent
- Brokerage, if applicable
- Moving expenses
The initial requirement can be considerably lower than buying a property.
A home purchase can require a substantial amount for:
- Down payment
- Stamp duty
- Registration
- Applicable taxes
- Other purchase-related charges
- Interior and furnishing
Therefore, renting can be easier for someone who has limited savings.
2. Flexibility
Renting provides greater flexibility.
If your job changes, you want to move closer to your workplace, or your family requirements change, moving from one rented property to another can be easier than selling a home.
This can be particularly useful for professionals whose careers involve frequent relocation.
3. Lower Responsibility for Major Repairs
Depending on the rental agreement, major structural or property-related maintenance may be the landlord’s responsibility.
A homeowner, however, is responsible for maintaining the property and paying applicable society or maintenance charges.
What Does Buying a Flat Give You?
Buying a home creates ownership.
Once the home loan is fully repaid, the homeowner owns the property without the outstanding loan.
But ownership also comes with responsibilities.
These can include:
- Home loan EMI
- Maintenance charges
- Property taxes
- Repairs
- Insurance, if applicable
- Registration-related expenses
- Interior costs
- Other ownership expenses
Therefore, home ownership should be viewed as a long-term financial commitment, not simply as an alternative to rent.
EMI vs Rent Example for 2026
Let’s consider an illustrative example.
Suppose a 2 BHK flat in Greater Noida West costs:
₹50 lakh
Assume the buyer makes a down payment and takes a home loan for the remaining amount.
The actual EMI will depend on:
- Loan amount
- Interest rate
- Loan tenure
- Lender
- Buyer’s credit profile
For illustration only, suppose the EMI works out to approximately ₹30,000–₹35,000 per month.
Now compare that with rent.
Suppose a similar property is available for:
₹20,000–₹25,000 per month
The tenant may save ₹5,000–₹15,000 every month compared with the EMI.
But the homeowner is acquiring an asset.
The renter retains the money that would otherwise go toward the down payment and additional purchase expenses, which can potentially be invested elsewhere.
This is why the correct comparison is:
Rent + Investment of Savings
versus
EMI + Property Ownership
rather than simply:
Rent vs EMI
The Importance of Down Payment
The down payment is one of the biggest differences between renting and buying.
Suppose:
Property price = ₹50 lakh
If the buyer contributes ₹10 lakh as a down payment, the remaining amount may be financed through a home loan, subject to lender eligibility and applicable lending rules.
But the buyer may also need funds for:
- Stamp duty
- Registration
- Applicable taxes
- Interior work
- Furniture
- Moving
- Other charges
Therefore, a buyer should not use every rupee of savings for the down payment.
It is sensible to maintain an emergency fund for unexpected expenses.
Don’t Compare Only EMI With Rent
This is one of the most important points for homebuyers.
Suppose:
Rent = ₹22,000/month
and
EMI = ₹32,000/month
The difference is:
₹10,000/month
But buying also involves ownership costs.
These may include:
- Maintenance
- Repairs
- Property taxes
- Insurance
- Opportunity cost of down payment
- Registration expenses
- Interior expenses
At the same time, rent can increase over the years.
Therefore, the comparison should be made over a longer period rather than based on one month’s payment.
Rent Can Increase Over Time
Rent is not necessarily fixed forever.
Depending on the rental agreement and local market conditions, rent can increase periodically.
For example, if a tenant starts at:
₹20,000 per month
and rent increases over time, the monthly cost after several years could be considerably higher.
This is one reason long-term tenants should consider how rent escalation may affect their future budget.
However, buyers should also remember that property ownership has increasing costs such as maintenance and repairs.
EMI Can Also Change
A home loan EMI is not always guaranteed to remain unchanged for the entire loan period.
For floating-rate loans, changes in interest rates can affect:
- EMI amount
- Loan tenure
- Total interest payable
The exact impact depends on the lender and loan structure.
Before taking a home loan, understand whether the loan is fixed, floating, or structured differently and how changes in interest rates may affect you.
Tax Benefits of Home Loans
Home loan borrowers may be eligible for certain tax benefits depending on prevailing tax laws, the property, loan structure, and the taxpayer’s circumstances.
Potential benefits can relate to:
- Principal repayment
- Home loan interest
- Self-occupied property
- Let-out property
However, tax rules and individual eligibility can vary.
Therefore, buyers should not purchase a property solely because of expected tax benefits.
Tax treatment should be considered as one part of the overall financial calculation.
Property Appreciation: An Important Difference
One major potential advantage of buying is property appreciation.
If the value of a property increases over time, the homeowner may benefit from capital appreciation.
For example, if a property purchased for ₹50 lakh eventually becomes worth ₹65 lakh, the homeowner has potentially gained ₹15 lakh in property value before considering transaction costs and other factors.
But appreciation is not guaranteed.
Property prices can:
- Increase
- Remain stable
- Grow slowly
- Decline in some circumstances
Therefore, buyers should never assume that a property will automatically double or generate a specific return.
Location, infrastructure, supply, demand, project quality, market conditions and economic factors all influence property values.
What About Rental Yield?
For someone comparing buying versus renting, rental yield can also provide useful context.
Rental yield broadly compares annual rental income with the property’s value.
For example:
If a property worth ₹50 lakh generates annual rent of ₹2.40 lakh:
Rental yield = ₹2.40 lakh ÷ ₹50 lakh × 100
This equals approximately 4.8% before considering expenses.
Actual rental yields vary by property, location, apartment size, furnishing, demand and market conditions.
This calculation can help investors understand whether a property’s rental income is attractive relative to its price.
When Renting May Be Better in 2026
Renting can make more sense when:
You May Move Soon
If you expect to relocate within a few years, buying and selling transaction costs may make ownership less attractive.
You Don’t Have Enough Savings
If buying would consume almost all your savings, renting may be financially safer.
EMI Would Be Too High
A home loan should fit comfortably within your monthly budget.
You Are Unsure About the Location
Renting first can allow you to understand:
- Traffic
- Connectivity
- Daily convenience
- Society environment
- Commute
- Nearby facilities
before committing to a purchase.
You Have Better Investment Opportunities
If you have a disciplined investment strategy and can potentially generate attractive returns from your savings, renting while investing the difference may be worth considering.
When Buying May Be Better in 2026
Buying can make more sense when:
You Plan to Stay Long Term
The longer you stay, the more time you have to spread the initial purchase costs over your ownership period.
You Have a Stable Income
A stable income can make long-term EMI commitments more manageable.
You Have a Healthy Down Payment
Having sufficient savings reduces the amount you need to borrow.
You Want Ownership
Some buyers value owning their home even when renting might appear cheaper in the short term.
You Want Greater Control
Homeowners generally have greater control over interiors, renovations and the use of their property, subject to society rules and applicable regulations.
You Want a Long-Term Asset
A residential property can become an important part of a family’s overall asset portfolio.
How Long Should You Plan to Stay?
Holding period is one of the most important factors in the rent-versus-buy decision.
If you expect to stay for only one or two years, renting may be more practical.
If you plan to stay for:
5 years, 10 years or longer
buying can become more attractive, depending on the purchase price and financing terms.
This is because the upfront costs of buying are spread across a longer period.
For example, registration and other transaction expenses can feel significant when you own a property for only two years but may be less significant when spread over a decade.
Greater Noida West: What Buyers Should Compare
If you are considering purchasing a home in Greater Noida West, don’t compare properties based only on EMI.
Check:
Location
- Connectivity
- Main roads
- Public transport
- Schools
- Hospitals
- Markets
- Employment hubs
Property
- Carpet area
- Layout
- Floor
- Ventilation
- Natural light
- Construction quality
Society
- Security
- Maintenance
- Parking
- Gym
- Clubhouse
- Green spaces
- Other facilities
Financial Cost
- Property price
- Down payment
- EMI
- Stamp duty
- Registration
- Applicable taxes
- Maintenance
- Interior costs
A ₹50 lakh property with a well-planned financial structure may be more suitable than a cheaper property that does not meet your family’s requirements.
How AMBR Homes Can Fit Into Your Home-Buying Decision
AMBR Homes offers residential housing options for buyers exploring homes in Greater Noida West.
If you are currently paying rent and considering buying a home, AMBR Homes properties can be evaluated using a complete cost approach.
Instead of asking:
“Is the EMI higher than my rent?”
ask:
“Can I comfortably afford the complete cost of ownership, and do I plan to stay long enough to make buying worthwhile?”
Consider:
- Property price
- Apartment size
- Location
- Possession status
- Amenities
- Maintenance
- Registration costs
- Home loan requirements
- Down payment
- Long-term family needs
This approach can help you make a decision based on your actual financial situation rather than a simple EMI-versus-rent calculation.
A Simple Rent vs Buy Checklist
Before choosing between renting and buying, answer these questions:
Financial Questions
- How much savings do I have?
- How much can I comfortably use for the down payment?
- What EMI can I afford?
- Do I have an emergency fund?
- What other loans am I currently paying?
Lifestyle Questions
- Will I stay in Greater Noida West for several years?
- Is my job/location stable?
- Do I need a larger home soon?
- Do I want freedom to relocate?
Property Questions
- What is the complete purchase cost?
- What is the expected rent for a comparable property?
- What are the maintenance charges?
- Is the property ready to move?
- What are the project’s location and connectivity advantages?
Investment Questions
- Could my down payment earn returns elsewhere?
- What is the potential rental demand?
- What is the property’s resale potential?
- Am I comfortable with property-market risk?
Common Mistakes When Comparing EMI and Rent
Mistake 1: Saying “EMI Is Wasted Money”
This is incorrect.
The interest component of an EMI is a financing cost, but the principal component reduces the outstanding loan.
At the same time, ownership has several additional costs.
The comparison needs to be more comprehensive.
Mistake 2: Assuming Property Prices Always Increase
Real estate does not guarantee appreciation.
A buyer should evaluate the property based on current fundamentals rather than assuming a specific future return.
Mistake 3: Ignoring the Down Payment
The opportunity cost of the down payment is important.
That money could otherwise be invested or kept as liquidity.
Mistake 4: Ignoring Rent Increases
Long-term rent should be evaluated rather than using only the current month’s rent.
Mistake 5: Taking an EMI That Is Too High
A home should improve your financial stability, not put your monthly finances under constant pressure.
Final Verdict: EMI or Rent in Greater Noida West in 2026?
There is no universal answer.
Rent may be better if you value flexibility, have limited savings, may relocate soon, or are not yet financially ready for a long-term home loan.
Buying may be better if you have stable income, sufficient savings, plan to stay for many years, and find a property whose total cost fits comfortably within your financial plan.
For many long-term homebuyers, the decision should ultimately come down to:
Affordability + Holding Period + Location + Property Quality + Long-Term Goals
If you are exploring a home in Greater Noida West, don’t choose a property simply because its EMI is close to your current rent.
Calculate the complete cost of ownership, compare it with the cost of renting, consider what happens to your savings and investments, and then make the decision.
Conclusion
The Home Loan EMI vs Rent in Greater Noida West question is not simply about which monthly payment is lower.
Rent gives flexibility and lower upfront costs. Buying gives ownership but requires a larger initial investment and a long-term financial commitment.
In 2026, the right choice depends on your individual circumstances.
If you are financially prepared, expect to stay in Greater Noida West for the long term, and find a suitable property at a reasonable overall cost, buying a home can be a meaningful long-term decision.